Money talk with your partner: 10-minute plan
Talking about money with your partner doesn't have to be hard. Use this ten-minute plan to get aligned on finances.
By the UNest team · 3 min read

Talking money with a partner can feel awkward, but avoiding it often causes bigger problems later. Strong couples do not avoid finance; they make it less scary and more routine. In just 10 minutes, you can kick off alignment around one of your shared dreams: saving for your child’s future.
Below is a simple conversation plan, plus phrases to use (and to avoid), to help you both move forward without defensiveness. At the end: a gentle nudge to open a UNest UTMA and start contributing together.
The 10-Minute Conversation Plan: Outline & Tips
- 0:00–1:00 | Set tone & intention: “Hey, can we take 10 minutes to talk about how we want to handle savings for the baby? I don’t want this to be heavy, just to get us on the same page.”Goal: Frame the talk as collaborative, short, and not blame.
- 1:00–2:30 | Share money stories / attitudes: “Growing up, my parents saved, spent, or avoided talking about money. That shaped me to feel ___.” Ask your partner: “What about you?”Goal: Understand each other’s background without judgment.
- 2:30–4:00 | Vision & priorities: “What do we want for the child in 5, 10, or 18 years? Education? Travel? A safety net?”Goal: Create shared goals.
- 4:00–5:30 | Current state (assets / debts): “Here’s what we have now in savings and investments. Are there liabilities I should know about?”Goal: Transparency and no surprises later.
- 5:30–7:00 | Decide roles & mechanics: “Who will contribute? How often? Where do we hold it? Do we set up automatic transfers?”Goal: Make the plan concrete.
- 7:00–8:30 | Address concerns / objections: “What worries you about doing this?” Listen. “I hear you. Let’s figure out a guardrail we both feel safe with.”Goal: Diffuse resistance and validate feelings.
- 8:30–10:00 | Commit & next steps: “Let’s each commit $X per month, or begin with a small amount. I’ll open the UTMA. We’ll check in in three months to adjust.”Goal: Agreement and accountability.
Tips to make it smoother:
- Pick a relaxed time without tension or distractions.
- Use “we” language instead of “you” or “me.”
- If the talk gets heated, pause and come back later.
- Be okay with starting small. Momentum matters more than perfection.
- Set a recurring “money check-in” so it becomes routine.
Ready to start saving for your child?
Open a custodial account in minutes and invest a little each month.
Get StartedSoftening language: “Say this. Don’t say that.”
- Say this: “I want us to align on this together.”Don’t say: “You need to do this my way.”
- Say this: “What worries you about contributing more?”Don’t say: “Why are you reluctant to save more?”
- Say this: “Let’s start small so it doesn’t feel overwhelming.”Don’t say: “We should dump all extra money into this at once.”
- Say this: “I hear your concern about liquidity. Maybe we do a buffer fund too.”Don’t say: “You’re being unrealistic or too conservative.”
- Say this: “I’m open to your ideas and adjustments.”Don’t say: “We’re doing it this way, end of story.”
- Say this: “We can revisit this and make changes.”Don’t say: “This is permanent, no revisiting.”
Avoid framing disagreements as conflict. Treat them as discovery: “Help me understand your view.”
The Nest Egg.
The UNest newsletter
A short read with money news for families, ideas for parents, simple activities to do with your kids, and updates on UNest features.
Free. Unsubscribe anytime. We’ll never share your email. Read our privacy policy.
Why use a UTMA for child savings
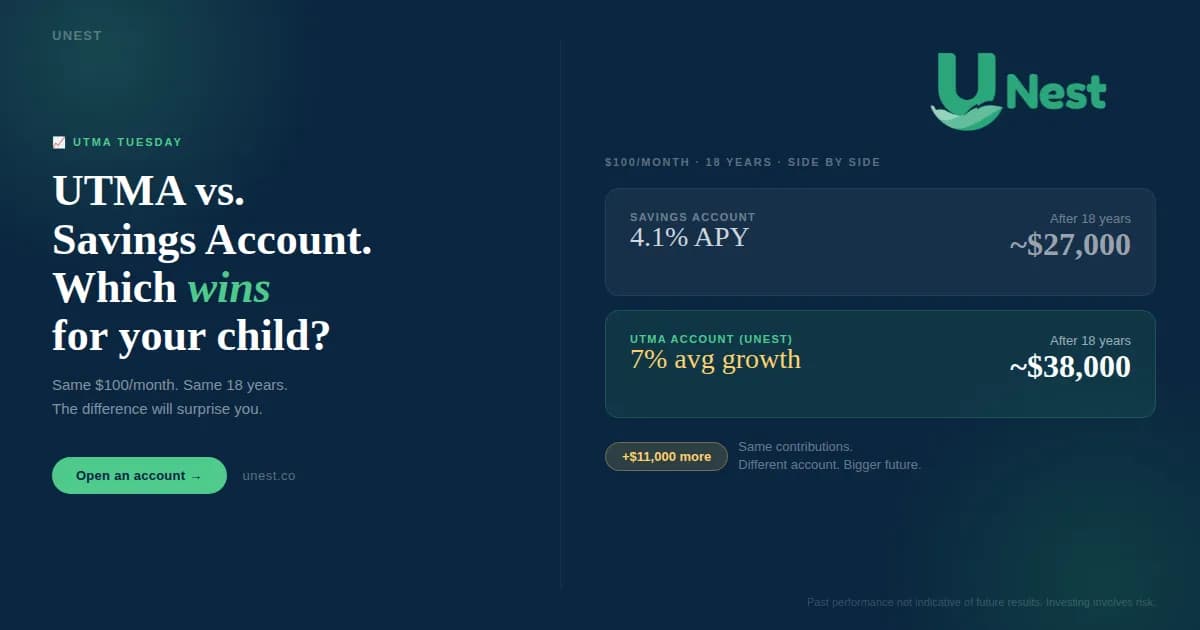
A UTMA (Uniform Transfers to Minors Act) account is a custodial account that lets you contribute money or assets for a minor until they reach the age of majority in your state. Unlike some education-only accounts, funds in a UTMA can be used broadly for anything benefiting the child.
Starting a UNest UTMA is a practical way to centralize child savings, automate contributions, and keep things transparent.
Try it tonight
If you try this 10-minute plan tonight, you may be surprised at how much clarity you gain and how much less anxiety future decisions bring.
If you are ready to act: **Open a **UNest UTMA and commit just $25 a month (or more, whatever fits your budget). Automating the contributions removes friction, and over time that consistency builds something meaningful for your child’s future.